Payday Lender Suing You?

Our Attorneys Can Help You Act On Time.
Fill in the form below or call us for a free review of your case.
FREE CASE EVALUATION
NO UPFRONT COST
01✓ Your debt
02✓ Your situation
03✓ Your details

How much do you currently owe in total?

An estimate is fine. It helps us understand your situation.
$8,000
$0 $100,000+
continue →
A woman stands at her kitchen counter with her arms crossed, looking out the window, her phone face-down beside a red mug.
FREE CASE EVALUATION · STEP 2 OF 3

Tell us what's been happening.

FREE CASE EVALUATION
NO UPFRONT COST
01✓ Your debt
02✓ Your situation
03✓ Your details

Tell us about the debt.

Please make sure all fields with (*) are selected to go to next step

How do we reach you?

FREE CASE EVALUATION
NO UPFRONT COST
01✓ Your debt
02✓ Your situation
03✓ Your details
10 digits Number is required
email@example.com format is required
Please enter valid 5 digit zip code
5-digit zip code is required
We currently do not service AK, DC, DE, HI, IA, ID, MD, ME, MT, NC, NE, VT, WV, WY
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.
Credo Legal Services, P.C. BBB Business Review

10 million+

IN DEBT WIPED

500k

DEBTS SETTLED EVERY MONTH

WHAT WE DO

Sued over a payday loan? We answer fast.

At Credo Legal, when you're sued over a payday loan, we act immediately. We review the lawsuit and the loan, then file your response before the deadline.
  • File your legal answer before the response deadline.
  • Review whether the payday loan was licensed and legal in your state.
  • Challenge inflated balances from fees, interest, and rollovers.
  • Defend you against default judgment and its consequences.
A person's hands writing with a pen in a notepad at a wooden table, beside a red mug and a letter.

WHY CREDO

Legal advice, not debt consolidation.

Licensed attorneys, we file

Your response is submitted before the deadline. We don't let that window close.

We know payday loan law

Payday loans are subject to specific state and federal rules. We examine the loan itself, not just the lawsuit.

We challenge the loan

Before we respond, we examine whether the lender was licensed, whether the rate was legal in your state.

Protection from default judgment

A default judgment enables wage garnishment and bank levies. We fight to prevent it.

Flexible payment plans

Attorney-led lawsuit defense structured around your budget.
    A wooden desk with a green banker's lamp, a notepad and pen, a leather-bound book and a coffee mug.

    WHY CREDO

    Common problems, and the line each one crosses.

    01
    FRCP 55

    Default judgment risk

    No response = the lender wins automatically, without proving the loan was valid or legally made.
    02
    FRCP 12(a)

    Expiring response deadlines

    20 to 28 days passes quickly. Courts rarely grant extensions once it expires.
    03
    State payday law

    Inflated balances from rollovers

    A payday loan originally for a few hundred dollars may have grown into thousands through repeated rollovers.
    04
    State payday law

    Unlicensed or illegal lenders

    Some payday lenders operate without a license or charge above the legal rate in your state, making the loan voidable.
    06
    FRE 803(6), 901

    Loans sold to collectors

    The entity suing you may be a debt buyer who purchased the loan, with incomplete documentation.
    06
    15 U.S.C. § 1673

    Garnishment exposure

    A default judgment opens the door to wage garnishment and bank account levies immediately.

    Who this helps

    You'll recognize your own situation here.

    • Anyone who has received a summons or court papers for a payday loan lawsuit.
    • People whose payday loan balance has grown far beyond the original amount through fees and rollovers.
    • Those who borrowed from an online lender and aren't sure whether it was licensed in their state.
    • Anyone who ignored early notices and is now facing a default judgment deadline.
    • People who want the loan and the lawsuit independently reviewed before paying anything.
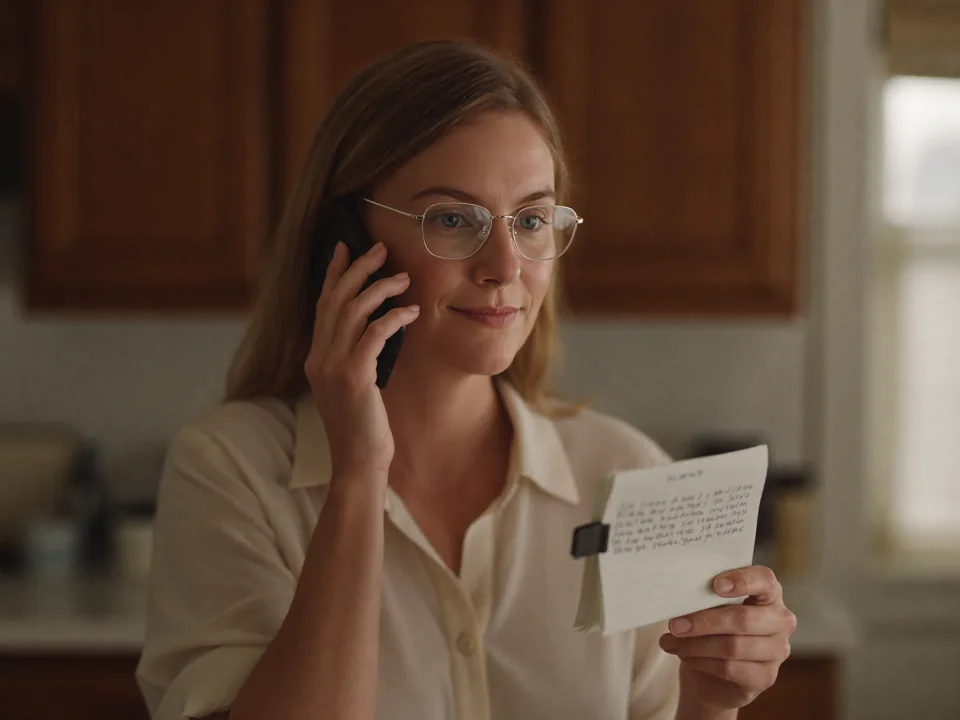
    A woman in glasses talks on the phone in her kitchen while reading a handwritten note.

    how it works

    A clear sequence, on a known timeline.

    01

    Free consultation

    Tell us about the lawsuit. We review the complaint and the loan at no cost.
    DAY 0

    02

    Loan investigation

    Our attorneys examine the loan for licensing issues, rate violations, inflated fees, and documentation gaps.
    Week 1

    03

    Legal response filed

    We file your answer before the deadline, incorporating every defense we've identified.
    BY DEADLINE

    04

    Resolution

    We fight in court, negotiate a settlement, or pursue dismissal, based on what the review finds.
    ONGOING

    10 million+

    IN DEBT WIPED

    500k

    DEBTS SETTLED EVERY MONTH

    Your rights

    Even after a payday loan lawsuit is filed, significant legal protections remain available.

    Civil right

    Right to respond + counsel

    You have the right to respond to the lawsuit and be represented by an attorney in court.

    RIGHT
    File an answer. Be heard. Force the lender to prove the case.
    State payday law

    Unlicensed lender forfeits

    The lender must prove the loan was legally made and properly documented. In many states, unlicensed lenders forfeit the right to collect.

    Right
    Unlicensed lender = potential void of the entire claim.
    State usury law

    Rate caps + payday rules

    State usury and payday lending laws set rate caps and licensing requirements. A loan made in violation may be void or voidable.

    Right
    Above-cap rate = potential void of the interest, sometimes principal too.
    Chain of assignment

    Standing for debt buyers

    If the debt was sold to a collector, they must prove an unbroken, documented chain of ownership.

    Right
    Multiple sales without documentation = standing problem.
    CFPB rules

    Disclosure requirements

    CFPB regulations require specific disclosures and lending practices. Violations can be raised as defenses.

    Right
    Missing or inadequate ability-to-repay assessment = potential defense.
    FRCP 60(b)

    Vacating a judgment

    A default judgment, while serious, can sometimes be vacated with prompt legal action.

    Right
    Improper service, mistake, excusable neglect, narrow but real grounds.

    Frequently asked

    Questions, answered plainly.

    What happens if I don't respond to a payday loan lawsuit?

    The court enters a default judgment automatically. This gives the lender or collector the right to garnish wages and levy bank accounts, without ever having to prove the loan was valid.

    How long do I have to respond?

    Typically 20 to 28 days from the date you were served, depending on your state. The clock starts the day of service.

    Can a payday loan be challenged if I actually borrowed the money?

    Yes, in many cases. The original loan amount may be legally disputed if the lender was unlicensed, if the rate was above the state cap, or if disclosures were inadequate.

    What if I borrowed from an online lender I found through an ad?

    Online payday lenders are required to be licensed in the state where the borrower lives. Many are not. Lack of licensing where you live can void the loan.

    How much does this cost?

    Your consultation is free. We offer flexible payment plans and will explain every option before any commitment.

    Ready when you are

    Know your rights before you make any decision.

    Filing a response is the most important thing that can happen right now. Our attorneys act fast and explain the path forward.
    ‍
    GET A FREE CASE EVALUATION →
    Credo Legal Services, P.C.
    1 Liberty Street, Suite 4010, New York, NY 10006
    This is attorney advertising. Prior results do not guarantee a similar outcome. Credo Legal is a multi-jurisdictional law firm. Communication through this site does not create an attorney–client relationship. Not a debt-settlement company. Not a credit-counseling service.

    WE CURRENTLY DO NOT SERVICE AK, DC, DE, HI, IA, ID, MD, ME, MT, NC, NE, VT, WV, OR WY.
    © 2026 Credo Legal. All rights reserved.
    Attorney Advertising